Autistic individuals and their families may face unique financial and tax-related considerations, particularly when public benefits, self-employment, disability-related savings, and changing federal tax laws intersect. Recent changes under the One Big Beautiful Bill Act (OBBBA) make it especially important to understand current provisions that may affect financial planning.
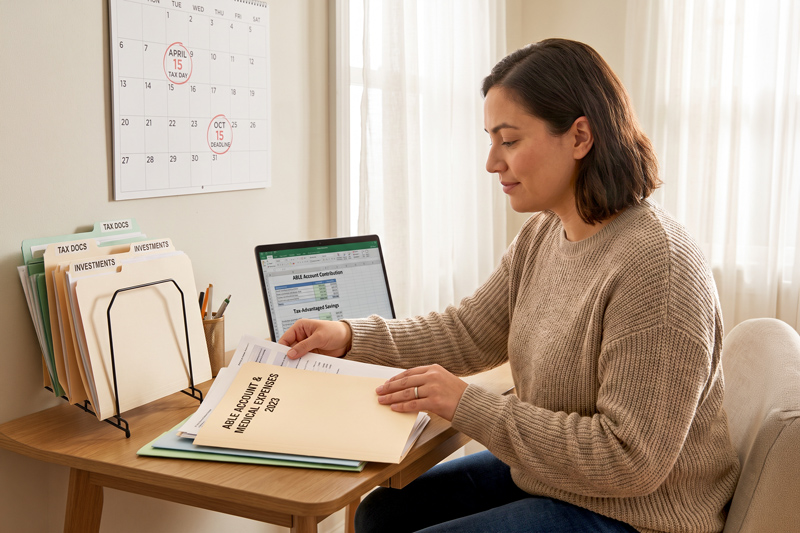
This article has two aims: first, to highlight selected tax provisions and recent legislative changes relevant to autistic individuals and their families; and second, to address practical strategies for navigating tax season, including organization, deadlines, filing requirements, and professional support.
General Issues and Concerns
Those with differing abilities may have financial concerns above and beyond the average person. There are some tax benefits available to this group and also some unusual forms of income generation which may be beneficial for them to consider. They must also be aware and fully informed of what may or may not affect some very important benefits such as Supplemental Security Income (SSI) and Medicaid.
Generating income as an independent contractor (sometimes referred to as “gig” work) requires knowledge that may be outside the scope of the neuro-diverse and their families. The immediate thought that comes to mind is income that is reported to them on Form 1099, as opposed to Form W-2, which does not include withholding of any taxes. This includes state and federal income taxes as well as the required Social Security and Medicare taxes, which for self-employed individuals are referred to as “self-employment” tax. Those taxes must be paid quarterly in the form of estimates to the governing authorities to avoid penalties and interest for late payments.
Another important factor to consider with self-employment is which expenses can be legitimately deducted from this income to determine the taxable portion upon which to compute and pay estimated taxes. Generally, any expense that is directly related to the generation of this income may be deducted, such as advertising, insurance (other than health), legal and professional services related to the income, office supplies, and utilities, to name a few. Office-in-the-home expenses are a very complex issue that requires individual consultation with a tax provider.
Some favorable tax regulations available to the neuro-diverse are known as the ABLE Act accounts and the Saver’s Credit. Both of these are summarized below:
ABLE Act
Achieving a Better Life Experience (ABLE) Act established ABLE accounts in 2014. The ABLE Act allows individuals to establish an ABLE account if they have a diagnosed disability that was diagnosed by the time the individual attained the age of 26 (Gardner & Daff, 2015). Effective January 1, 2026, the ABLE Age Adjustment Act raised this age-of-onset threshold from 26 to 46. When the law was enacted, the eligible individual, also known as the designated beneficiary or owner of the account, is entitled to collect Social Security based on blindness or disability.
Saver’s Credit
The Saver’s Credit enacted under IRC Section 25B is a non-refundable credit available to certain eligible individuals who have made contributions to certain types of retirement programs — for example, 401(k), 403(b), 457(b), IRAs, Roth IRAs, and ABLE accounts, to name a few. The credit is available to taxpayers of at least 18 years of age who are not full-time students and who cannot be a qualifying child or qualifying relative for another taxpayer (Bird et al., 2019).
Effects of the One Big Beautiful Bill Act (OBBBA)
Earlier, there was a proposed bill being debated named the ENABLE Act with the intent to modify some of the provisions of the ABLE Act. The ENABLE Act was not adopted; instead, the proposed changes were incorporated into the OBBBA (Piacenti, 2025). The ABLE Act included provisions for many elements of the program to sunset at different dates, but the inclusion of the ENABLE Act in the OBBBA made ABLE accounts a permanent part of the tax code.
The provisions of the law now becoming permanent are: the ABLE to Work provision, which allows employed disabled individuals to contribute more than the annual standard limit; the ABLE Saver’s Credit, which allows low- and moderate-income individuals who contribute to their ABLE accounts to qualify for a tax credit; and 529 college savings plan to ABLE rollovers, which allows families to permanently roll over unused college savings into ABLE accounts without incurring tax penalties (Piacenti, 2025).
To summarize, the key takeaways are that ABLE accounts offer tax-free savings for disability-related expenses, the annual contribution limits are $20,000 annually plus up to $15,650 (for residents of the continental United States) for employed individuals who do not participate in a workplace retirement plan. Additionally, ABLE accounts with balances of $100,000 or less do not affect SSI benefits, and Medicaid benefits are not affected by an ABLE account regardless of the balance in the account. Also, the OBBBA made the provisions discussed above permanent.
Managing Tax Obligations and Tax Season
The tax code can be understood, in part, as a system of incentives and consequences: it offers credits, deductions, and tax-advantaged savings opportunities, while imposing penalties and interest when filing or payment obligations are not met. For autistic adults, these demands may intersect with broader financial challenges, including financial stress and difficulty with planning and decision-making (Cai et al., 2024; Pellicano et al., 2024).
Tax benefits are only useful when taxpayers are able to successfully navigate the filing process. For some autistic individuals (and other people overwhelmed with financial matters), executive functioning demands associated with taxes include things like organizing documents, tracking deadlines, initiating tasks, responding to correspondence, and managing multiple steps over an extended period. Balancing public benefits, self-employment, or navigating a move or address change during tax season may further complicate these demands.
These also present additional challenges when individuals and their families are managing varying levels of financial literacy. Galizzi et al. (2023) found that “autistic adults showed lower financial literacy and greater uncertainty around many financial issues. They were less confident in their financial knowledge and ability to deal with daily financial matters.” Developing a more predictable system well before tax season can reduce both stress and the likelihood of costly errors. Building on these findings, three practical strategies may help autistic individuals and their families make tax preparation more manageable and reduce the risk of missed deadlines or other avoidable problems:
- Start early and externalize deadlines. Put April 15 (or even April 1 to buy yourself some), estimated-tax dates, and any extension deadline into a calendar well in advance. Use multiple reminders and break tax preparation into smaller tasks, such as gathering forms, reviewing income, identifying deductions, and scheduling preparation.
- Create a consistent tax organization system. Keep W-2s, 1099s, benefit statements, receipts, and prior returns in one designated physical or electronic location. A predictable system can reduce the executive-functioning burden of searching for documents and reconstructing information at filing time.
- Develop an ongoing relationship with a qualified tax professional who understands your needs. Rather than seeking assistance only when – or even after — a deadline or tax notice arises, autistic individuals and families may benefit from working consistently with a CPA, Enrolled Agent, or other qualified tax professional who understands their financial situation, benefit considerations, and support needs. This can also help identify estimated-tax requirements, filing issues, and planning opportunities earlier in the year.
Taken together, effective tax planning involves both understanding the benefits and obligations created by current tax law and developing practical systems for managing them. For autistic individuals and their families, the goal should be to use the tax code strategically — to take advantage of available benefits, credits, and savings opportunities — rather than allowing missed deadlines, inadequate planning, or avoidable penalties to create additional financial burdens.
William Leonelli, EdD, MS, CPA, is an Assistant Professor of Human Services and Human Services Leadership at St. Joseph’s University, New York. He is a Certified Public Accountant with professional experience in accounting and financial management and previously served as Chief Financial Officer of Long Island Cares. His scholarly work has also examined the preparation of higher-education faculty to support students with disabilities and diverse learning needs. To contact Dr. Leonelli, email [email protected].
Harry M. Voulgarakis, PhD, BCBA-D, is an Associate Professor in the Department of Child Study at St. Joseph’s University, New York, as well as a licensed psychologist, Board Certified Behavior Analyst, and IRS Enrolled Agent. His clinical and scholarly work focuses on neurodevelopmental disorders, child and family functioning, and health-related concerns. To contact Dr. Voulgarakis, email [email protected].
References
Bird, B. M., Hopper, M., Colley, R., Hodges, C., & Mehanaou, M. (2019). IRC Section 25B Can Help Eligible Taxpayers Save for Retirement. Journal of Taxation, 131(6), 24-28. https://www.proquest.com/docview/2323404641
Cai, R. Y., Hall, G., & Pellicano, E. (2024). Predicting the financial wellbeing of autistic adults: Part I. Autism, 28(5). https://doi.org/10.1177/13623613231196085
Galizzi, M., Hillier, A., & Schena, D., II. (2023). Financial literacy among autistic adults. Journal of Consumer Affairs, 57(4), 1650–1683. https://doi.org/10.1111/joca.12564
Gardner, R., & Daff, L. (2015). ABLE Accounts: An Option for Families with Disabled Children. Journal of Financial Planning, 28(2), 30, 32–33.
Pellicano, E., Hall, G., & Cai, R. Y. (2024). Autistic adults’ experiences of financial wellbeing: Part II. Autism, 28(5). https://doi.org/10.1177/13623613231191594
Piacenti, K., C.H.S.N.C®. (2025, 11). Empowering Financial Independence: ABLE Accounts and the Impact of the One Big Beautiful Bill. The Exceptional Parent (Online), 55, 22-23. https://www.proquest.com/docview/3281533266