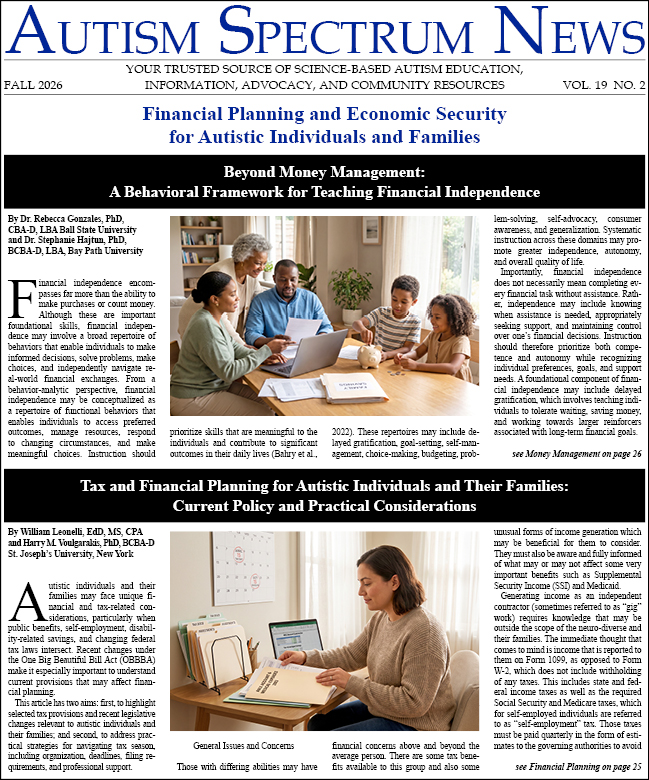
The financial systems that support a child mostly disappear at eighteen. Here’s how families can plan for the system that replaces them.
Most of the financial planning conversations that happen in early intervention and school-age ABA services are, understandably, focused on the here and now: how many therapy hours are authorized this month, which services insurance will cover this year, how to budget for the next evaluation. Adulthood can feel far away when a family is still navigating an IEP meeting or a new diagnosis.
But adulthood arrives faster than most families expect, and the financial systems that support a child, such as insurance mandates, school-based services, and pediatric Medicaid rules, mostly disappear at eighteen or twenty-one. What replaces them is a different, less familiar system, and families who haven’t started planning for it often find themselves scrambling during a period that should otherwise be a proud transition.
The guidance below reflects patterns seen consistently across ABA clinics working with families well before, and well after, that transition point. These are general observations, not personalized financial, legal, or investment advice — every family’s benefit rules, assets, and legal situation are different, so it’s worth confirming anything specific to your circumstances with a licensed financial advisor, a special needs planning attorney, or the relevant benefits agency directly.
Start Earlier Than Feels Necessary
The single most common regret voiced by families of autistic adults is not starting the planning process sooner. Many of the most important financial protections, such as guardianship or supported decision-making arrangements, special needs trusts, and adult Medicaid waiver applications, take months or years to set up properly, and several have waitlists that start counting from the date of application, not the date of need.
Recommendation: Begin having exploratory conversations, even informal ones, by early adolescence. This doesn’t mean committing to specific legal decisions years in advance. It means starting to ask the right questions early enough that decisions can be made thoughtfully rather than under deadline pressure as a child approaches eighteen.
Understand That Benefits Rules Change at Adulthood
Many families don’t realize that eligibility for programs like Supplemental Security Income (SSI) and Medicaid is calculated differently once a child turns eighteen. Before that age, a parent’s income and assets are usually counted against eligibility. After eighteen, in most cases, only the individual’s own income and assets are counted, which means an autistic adult with no income of their own may newly qualify for benefits that weren’t available during childhood, even in households with solid incomes.
This shift is good news for many families, but it also introduces new risk. A well-intentioned gift, an inheritance, or savings placed directly in an adult child’s name can push them over asset limits (often just a few thousand dollars) and result in a loss of benefits.
Recommendation: Around age seventeen, meet with a benefits counselor or a special needs planning attorney to understand exactly how eligibility will be recalculated. This is also the point to make sure any money set aside for the individual is held in a properly structured account, such as a Special Needs Trust or an ABLE account, rather than in a personal savings account in their name.
Special Needs Trusts and ABLE Accounts Serve Different Purposes
These two financial tools come up constantly in family planning conversations, and they are frequently confused with one another. A Special Needs Trust (sometimes called a Supplemental Needs Trust) is typically used to hold larger sums, an inheritance, life insurance proceeds, or settlement funds, and is usually set up with the help of an attorney. An ABLE account is a tax-advantaged savings account, similar in spirit to a 529 college savings plan, that allows for smaller, more flexible day-to-day contributions and withdrawals without the same legal overhead.
Families sometimes assume they need to choose one or the other. In practice, many families use both: an ABLE account for accessible, everyday savings, and a trust for larger assets meant to support the individual over decades.
Recommendation: Ask a special needs planning attorney or financial advisor to explain both tools side by side, specifically how they interact with SSI and Medicaid eligibility, before assuming either one alone is sufficient.
Guardianship Is Not the Only Option, and It’s Not Always Necessary
As children with more significant support needs approach eighteen, many families are told that guardianship is simply the next step, sometimes without a full explanation of what it involves or what alternatives exist. Guardianship transfers a range of legal decision-making authority from the individual to the guardian and can be difficult to reverse or narrow later.
For many autistic adults, less restrictive alternatives, such as supported decision-making agreements, power of attorney for specific matters, or a representative payee arrangement for benefits, may accomplish the same practical goals while preserving more of the individual’s autonomy.
Recommendation: Before pursuing full guardianship, ask an attorney familiar with disability law to walk through the full range of decision-making support options available in your state, and consider which level of support actually matches your child’s abilities and needs, rather than defaulting to the most restrictive option because it’s the most commonly discussed.
Employment and Day Programs Have Real Financial Implications
Families are sometimes surprised to learn that an adult child’s earned income, even modest income from a part-time job or a day program with a stipend, can affect SSI and Medicaid eligibility if it isn’t managed carefully. This sometimes leads families to avoid encouraging employment altogether, out of fear of losing benefits, even when work would be meaningful and appropriate for their child.
In most cases, SSI includes work incentive provisions that allow for some earned income without an automatic loss of benefits, and several are specifically designed to make employment viable rather than penalized.
Recommendation: Before assuming employment isn’t financially viable, consult a benefits planning specialist (often called a Work Incentives Planning and Assistance, or WIPA, counselor) who can calculate the actual impact of a specific job or program on benefits, rather than relying on general assumptions.
Teaching Financial Independence Directly
Much of the planning above focuses on structures built around an autistic adult: trusts, accounts, benefits coordination. But clinical teams increasingly see the value in also building financial skills with the individual directly, to whatever degree fits their abilities. Skipping this step isn’t a neutral choice; it often means an adult who could have managed a debit card, a weekly budget, or a simple bill payment ends up more financially dependent than necessary, not because of ability, but because no one taught the skill.
What this looks like varies widely. For some, it means practicing recognizing coins and bills, or using a visual budgeting system to understand that money is finite. For others, it means managing a checking account, comparing prices while shopping, or understanding what a bill is and when it’s due. Many ABA and life-skills programs now build these goals directly into treatment or transition planning, as part of the broader work of teaching daily living skills through ABA, since financial tasks can be broken into the same kind of teachable steps as any other skill.
Recommendation: Ask the clinical or transition team whether money-management goals, appropriate to the individual’s current skill level, are part of the treatment or IEP transition plan, and revisit them regularly as skills grow. Even small, consistent gains in financial independence can reduce reliance on caregivers over time and are worth treating as seriously as any other life-skills goal.
Build a Team, Not Just a Plan
One pattern seen repeatedly in clinical practice is a family that has one piece of the plan in place, a will, perhaps, or a trust, but not the others, and no single professional coordinating across the pieces. A trust set up without coordination with a benefits counselor can unintentionally affect eligibility. A guardianship petition filed without consulting the individual’s clinical team can miss important context about their actual capabilities.
Recommendation: Where possible, build a small team that includes a special needs planning attorney, a financial advisor familiar with disability benefits, and the individual’s current or former clinical team, and encourage them to communicate directly with one another rather than relying on the family to relay information between disconnected professionals.
Building Security Over Time
Financial security beyond childhood isn’t built in a single meeting or a single document. It’s built gradually, through conversations that ideally start years before they feel urgent, and through a coordinated team that understands both the legal landscape and the individual’s actual needs and strengths. Families who start this process early, even imperfectly, consistently report feeling more prepared and less overwhelmed than those who wait until a milestone birthday forces the issue.
For more information, visit www.kennedyaba.com.