When my son AJ was diagnosed with autism at age three, my wife and I focused on what was immediately in front of us: signing him up for the right therapies, navigating IEP meetings, finding activities he enjoyed, and helping him build skills. Like many parents, we were thinking about his future, but mostly in terms of the next few years. Thinking about what his life would look like 20, 30, or 50 years later was much harder.
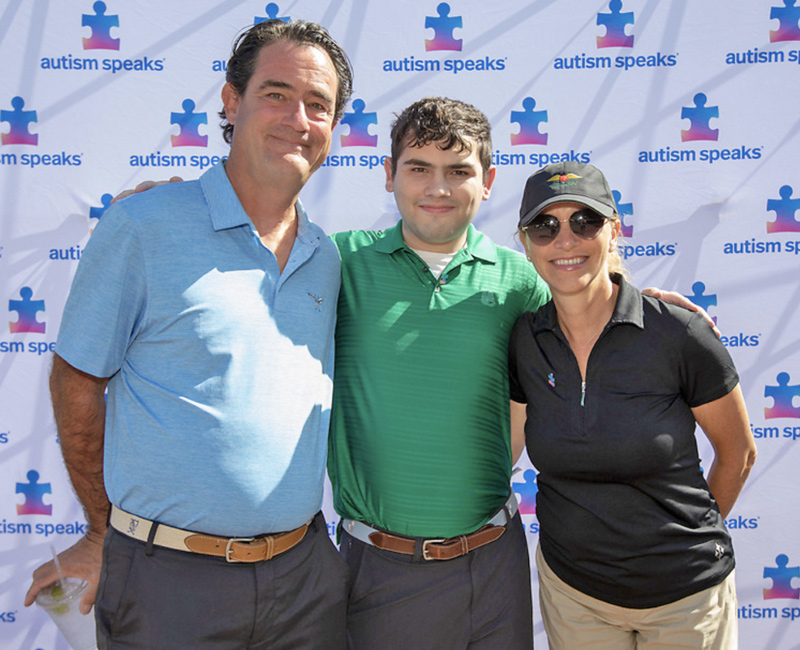
Pictured: Keith Wargo with his son AJ and wife Anne.
Autism is a lifelong condition, but there is no single trajectory for autistic people. Some people with autism live independently, build careers, and manage their own finances. Others need significant, lifelong support. Many people will need different levels of support at different points in their lives.
That uncertainty is exactly why planning for the future matters. It is also why there is no single financial roadmap that works for every autistic person or every family.
Start Earlier Than You Think
One of the biggest mistakes families can make is waiting for a crisis or major transition before they start future planning. Starting earlier gives families more time to understand their options, make thoughtful decisions, and adjust their plans as circumstances change.
In our family, financial planning meant more than setting money aside. It meant figuring out what supports AJ might need, learning about and applying for government benefits, setting up a life insurance policy, and building a network of people who could help us navigate the years ahead.
Families should start planning for the future as early as possible, ideally during the teen years.
None of those decisions happened all at once, and none of them came from having a perfect picture of AJ’s future. What we thought he might need as a child is not necessarily what he needs today. We simply made the best decisions we could with the information we had.
Families can do the same by starting to learn about the systems they may encounter as their child grows up. That might mean thinking about what supports their child could need in adulthood, what benefits or other resources might be available, and what they should know about employment, housing, and healthcare. It also means considering who could be part of their child’s long-term support network and what legal or financial arrangements may eventually be needed.
Autism Speaks’ Transition to Adulthood resources, including our Financial Planning Tool Kit, can help families start to answer these questions and prepare for the changes that come with adulthood well before their children leave school.
Understand the Programs Before You Need Them
For many autistic people, public benefits can be an important part of financial security. These programs all have different eligibility rules, and understanding what they provide (and how they work together) is essential for long-term planning.
Supplemental Security Income (SSI) is a needs-based federal program for people who meet disability and financial eligibility requirements. The federal SSI resource limit is $2,000 for one person, although not every asset counts toward that limit. That figure has not changed since 1989.
Medicaid is another important piece of the picture. In addition to providing health coverage, Medicaid can cover home- and community-based services (HCBS) in many states. These services may include respite, case management, and supported employment. People who receive SSI are generally eligible for Medicaid, but states have different rules and options for covering people with disabilities.
Social Security Disability Insurance (SSDI) is different. Eligibility generally depends on a person meeting Social Security’s definition of disability and having sufficient work history. In some circumstances, an adult whose disability began before age 22 may also qualify for benefits based on a parent’s Social Security record, once that parent retires, becomes disabled, or dies.
It’s also important to understand how benefits interact with other sources of financial support. A financial gift or inheritance, for example, can sometimes affect eligibility for benefits if it is not structured appropriately. Programs can also open doors to one another. In most states, people who receive SSI are categorically eligible for SNAP, which means their SSI approval satisfies the income and asset tests — though they still have to apply.
Because benefit programs, tax rules, and state laws can interact in complicated ways, families may benefit from working with a qualified financial planner, benefits specialist, or attorney with experience in disability planning. The right guidance can help families understand their options and make decisions that fit their circumstances.
My own family experienced how much time and effort it can take to navigate these systems. When we applied for benefits for AJ, the process took roughly three years and involved significant paperwork, meetings, and documentation. That’s one reason I encourage families to learn about these programs before they urgently need them.
Know the Tools, but Don’t Treat Them as One-Size-Fits-All Solutions
Once families understand the broader benefits landscape, they can start thinking about some of the financial tools that can help them prepare for the future. Two tools that come up frequently in disability planning are special needs trusts and ABLE accounts. Both can play an important role, but they serve different purposes, and neither is the right fit for every person or family.
A properly structured special needs trust can allow families to set aside money for the benefit of a person with a disability while preserving eligibility for certain public benefits that have income or asset limits. How the trust is funded matters. A trust funded with family assets works differently from one funded with the person’s own money (an inheritance left directly to them, for example, or a legal settlement), which is generally subject to Medicaid repayment after their death. For our family, establishing a trust was an important part of planning for AJ’s future. We also purchased a life insurance policy designed to fund the trust when my wife and I are both gone.
Decisions about whether to establish a trust, how to fund it, and who should serve as trustee should be made with qualified legal and financial guidance. Autism Speaks’ resource on special needs trusts provides an introduction to how these trusts work and questions families may want to consider.
ABLE accounts offer another way for eligible people with disabilities to save and pay for qualified expenses while maintaining access to certain public benefits. Beginning in 2026, the age at which a person’s disability must have begun to qualify for an ABLE account increased from before age 26 to before age 46. For 2026, the standard annual contribution limit is $20,000, and people receiving SSI can generally have up to $100,000 in an ABLE account without those funds counting toward the SSI resource limit.
For families who have already saved for education through a 529 account, there may also be an option to roll some of those funds into an ABLE account. The rollover counts toward the ABLE account’s annual contribution limit.
ABLE funds can be used for a broad range of qualified disability expenses, including housing, transportation, education, healthcare, employment supports, and other expenses related to living with a disability. While a trust can be useful for managing assets over the long term, an ABLE account can provide more flexibility for day-to-day expenses. In some cases, families may use both. Autism Speaks has worked for years to expand access to ABLE accounts and offers more information about ABLE accounts and the ABLE Act.
The right combination of tools will look different for every family. What matters is understanding the options available and considering how they can support the person’s needs, goals, and financial future. A professional who understands disability planning can help families determine which options make sense for them.
Plan for People, Not Just Accounts
For many parents, the financial questions are only the beginning. Families also have to think about who will be there to support their child and help navigate the future when they can no longer do it themselves.
For us, that question has meant thinking beyond money. My wife and I have had to consider who knows AJ well, who he trusts, what kinds of support he may need, and who can help him navigate decisions in the future. Those relationships are just as important to his long-term security as the financial tools we put in place.
Financial planning is only one piece of the puzzle—families should also think about the community they are building around their child.
We revisit our plans every few years. The plan we imagined when AJ was young looks very different from the one we have today. He is now 27, lives independently with some support, and works part time. When he was nine, I hoped those things might be possible, but his life has evolved in ways we could not have predicted — and our planning has had to evolve with him.
A long-term plan should leave room for the person to grow and change. For some autistic people, that may mean gradually taking on more responsibility for managing money and learning how to budget. For others who need more significant support, parents, caregivers, and other loved ones may need to take a more active role. The goal in either case should be to involve the autistic person as much as possible in the planning process.
Families should think about what happens if parents or other primary caregivers can no longer provide that support. That may mean identifying people who could step in, discussing who might serve as a trustee or successor trustee, considering powers of attorney or other legal decision-making arrangements, and making sure those people understand the autistic person and their wishes. Importantly, that does not mean assuming a sibling will automatically become a caregiver or trustee. Those are significant responsibilities, and families should have honest conversations about who is willing and able to take them on.
Ultimately, financial planning is not about building the perfect plan. It is about giving an autistic person the resources, support, and opportunities to build a fulfilling life — whatever that looks like for them.
This article is for general educational purposes only and does not constitute financial, tax, or legal advice. Eligibility rules and planning options vary by individual circumstances and may change over time. Autistic people and families should consult qualified professionals familiar with disability planning before making financial or legal decisions.
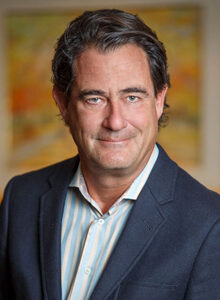
Keith Wargo is the President and CEO of Autism Speaks, working to create an inclusive world for all individuals with autism throughout their lifespan. For more information and resources, visit autismspeaks.org.