There is no one-size-fits-all approach to financial planning. Every person and family brings different goals, resources, responsibilities, and ideas about what financial security looks like. That is especially true when planning for or alongside a loved one on the autism spectrum.
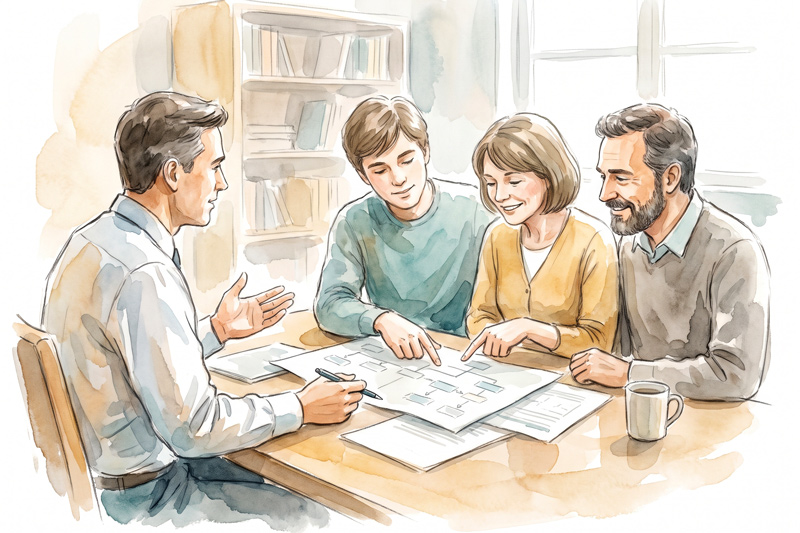
For an autistic person, the future may include living independently, pursuing a career, and managing their own finances. Others may need varying levels of day-to-day support, and those needs and goals may change over time. Effective financial planning begins with a few important questions: What does this individual want for their future? What support may help them get there? What resources are available today? And what should be put in place now to support financial security in the years ahead?
Answering these questions takes you beyond the basics of saving for education and retirement for an autistic person. Depending on their circumstances, you may also need to account for government benefits, healthcare and support costs, housing, estate planning, trusts, life insurance, and who will help manage financial decisions in the future.
Plan for Their Lifetime, Not a Season
Traditional financial planning often centers on retirement and investments. Planning for a family member with autism may require looking further ahead and asking a harder question: What happens when the people providing support today are no longer able to do so? The conversation may be uncomfortable, but delaying it does not make the need disappear.
Begin by considering what level of financial, healthcare, housing, and day-to-day support your loved one may need throughout adulthood. You should also consider who will provide that support and how it will be funded.
Support needs and family circumstances can change significantly over time, so a financial plan should not be created once and put on a shelf. Changes in employment, an unexpected health crisis, or another major life event may all require the plan to be revisited.
Starting early gives your investment strategy more time to grow and your family more time to understand available benefits and community resources before they are urgently needed. Waiting until an autistic child approaches adulthood can leave families scrambling to navigate programs and eligibility requirements that take time to understand and access.
Protect Their Benefits While Planning for the Future
Even well-intentioned financial decisions can have unintended consequences. For example, you may assume the simplest way to provide for an autistic child is to name them directly as an account beneficiary or leave assets to them through an estate. Depending on the individual’s circumstances, receiving assets directly may affect eligibility for certain government benefits or create challenges if they need help managing money.
You may want to explore special needs trusts with qualified professionals. A special needs trust provides a structure for assets to be managed on behalf of an autistic person. You can also plan for assets to fund the trust after your death, helping provide resources for their future needs.
The right solution depends on the individual, the benefits involved, your family’s assets, and other circumstances. The important point is to understand the implications before assets are transferred or beneficiary designations are made.
A certified financial planner or other wealth advisor experienced in special needs planning can help review retirement accounts, insurance policies, estate documents, and other assets so they work together as intended.
Remember That You Have a Future, Too
You naturally want to do everything possible to provide for your child. Planning for an autistic child’s future should not mean ignoring your own.
You may need your retirement savings to last for decades while also covering your own housing, healthcare, and long-term care needs. If those resources are exhausted to support an adult child, the financial security of both generations may be at risk.
There are many ways to approach this balance, and the right roadmap will depend on your family’s goals, resources, and support needs. A thoughtful plan can help you weigh those priorities together instead of treating them as competing concerns.
Consider what you will need to secure your own financial future and what resources your child might need as they grow into adulthood. What government support or community programs are available to help fill gaps?
Life insurance may also play a role. You may think of it as a way to replace income after an untimely death while your children are young. If you’re supporting an autistic loved one, it can also provide funds after a full life so financial support can continue for their future needs.
The goal is not to choose between your future and your child’s. It is to understand both and build a plan that considers them together.
Put the Autistic Individual at the Center
Financial planning is not only about providing for your child; it should also include them in the process whenever appropriate.
The appropriate level of involvement will differ from person to person. For those able to participate, financial literacy is an important part of that independence. Learning how to create a budget, pay bills, use credit responsibly, understand income, and manage everyday expenses are life skills that can be introduced long before someone is living on their own.
The earlier families create opportunities to practice those skills, the better prepared an individual may be when greater financial responsibility arrives.
Build a Team — and Keep Talking!
Financial planning for special needs crosses several disciplines; depending on your circumstances, your planning team might include a financial advisor or planner, estate-planning attorney, tax professional, healthcare provider(s), and professionals familiar with government benefit programs. Family members, caregivers, and others who know the autistic person well can provide equally important perspective.
The process starts simply with a conversation about what your child’s needs are today, hopes for the future, and what resources are already available. From there, trusted and experienced professionals can help identify gaps and determine which legal, financial, or support structures deserve further consideration.
You should also think about who will carry out the plan if the primary caregiver is unable to do so. Identify future trustees, guardians, or other trusted individuals, along with successors if the secondary caregiver is unable to take on that responsibility.
Your financial plan for your loved one should be structured enough to provide security and flexible enough to evolve alongside the person it is intended to support.
Employment opportunities, support needs, and family situations can all change. Your loved one’s goals may change, too, which is why the plan should be reviewed regularly and adjusted when appropriate.
Three Steps to Get Your Financial Plan Into Action
If you are wondering what you can do now, these three steps can help you begin putting your financial plan into action.
- Start with a conversation. You do not need every answer, or even every question, before getting started. A financial advisor or planner experienced in special needs planning can help identify your priorities, available resources and potential gaps. Other professionals, such as an estate-planning attorney, tax professional and/or benefits specialist, can then be brought in as needed. Beginning these conversations early may give you more time to understand your options and make informed decisions for your loved one.
- Review how assets will pass. Beneficiary designations, estate documents, special needs trusts and other planning tools should work together rather than inadvertently affecting benefits or leaving assets without appropriate oversight. Taking the process piece by piece can make it more manageable and help each decision support your loved one’s long-term security.
- Learn what resources are available. Government benefits and community support programs can be difficult to navigate, and families may not know what exists until they need help. Researching options early provides more time to understand eligibility requirements and consider how available resources may fit into the broader plan.
Successful financial planning is ultimately about creating confidence for the whole family. When the right structures are in place, resources are protected, benefits are preserved, responsibilities are clearly understood, and future decisions do not have to be made in crisis. And most importantly, a thoughtful plan gives your loved one greater opportunity to participate in shaping their own future, with support that can adapt as their needs, abilities, and goals change over time.
Marcus Benally, MBA, is Senior Manager of Client Advisory & Accounting Services at REDW Advisors & CPAs, with experience in financial literacy education and helping individuals build the knowledge and skills needed to make informed financial decisions.
James R. Karberg, CFP®, is Principal and Practice Leader of Wealth Management at REDW Advisors & CPAs, where he specializes in financial planning and tailored, tax-efficient wealth management strategies for individuals and families.